หมวดหมู่: Bookkeeping

  • Description of Transactional Analysis and Games by Dr Eric Berne MD

    transaction analysis

    TA believes that we have three different states or ways of being during interactions, which are; the child ego state, the parent ego state, and the state of adult (Berne, 1957). His ideas for TA developed from Sigmund Freud’s psychoanalytic theory that childhood experiences greatly impact our lives as adults and are the basis for the development of our personalities and psychological or emotional issues that we suffer. It does more than paint an accurate financial picture; it equips company executives to make educated choices. Accurate bookkeeping and financial accounting are crucial for proper recording of business transactions.

    Would you prefer to work with a financial professional remotely or in-person?

    The end result (an expense is reported and cash decreased) is the same, but the recording procedures differ. It would be impossible to emphasize the significance of precise transaction analysis in commercial accounting. Proper transaction analysis is crucial for creating accurate financial accounts. This can lead to incorrect log entries and mistakes in the accounting records.

    Examining the Ego States of Transactional Analysis
    transaction analysis

    As with any game, at least one party must achieve a “payoff” for the game to proceed. In this game, Mrs. White, and to a lesser degree Mr. White achieve their respective payoffs. In Mr. White’s case, by restricting Mrs. White’s activities, he can retain the role of domineering husband, which provides him comfort when things do not necessarily go his way. Mrs. White complained that her husband severely restricted her social activities, so that she had never learned to dance. Due to changes in her attitude brought about psychiatric treatment, her husband became less sure of himself and more indulgent.

    Books by Eric Berne (popular)

    Since the majority of the external events experienced by a child are actions of the parent, the ego state was appropriately called Parent. Note that events perceived by the child from individuals that are NOT parents (but who are often in parent-like roles) are also recorded in the Parent. When Transactional Analysts refer to the Parent ego state (as opposed to a biological or stepparent), it is capitalized. Due to the typically rational and reasonable nature of the Adult, Berne believes that the easiest and simplest transactions occur between Adult ego states, but transactions may occur between any of the three ego states. In a complementary transaction, the transaction response from the receiver is directed to the sending ego state in the speaker.

    • TA recognized that the human personality is made up of three “ego states,”; each of which is an entire system of thought, feeling, and behavior from which we interact with each other.
    • Nayeri, Lotfi, & Noorani (2014) provided 15 couples with group transactional analysis sessions.
    • For the sake of brevity, only the most relevant points will be discussed here.
    • Most of our webinars are free of charge and can be attended by all our members worldwide.
    • He developed this method for helping the patients (clients) who are under this therapy.
    • In the same way, Berne believed that our childhood experiences, particularly how we are parented, affect the developmental formation of our three ego states (Parent, Adult, and Child).

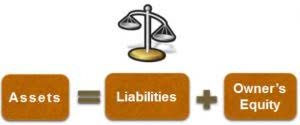
    This can then unconsciously cause us to replay the same attitudes and behaviors that our parents had towards us to someone else during a conversation or to respond to communication and interactions with past childhood anxieties and emotions. Unhealthy childhood experiences can lead to being pathologically fixated in the Child and Parent ego states, bringing discomfort to an individual and/or others in a variety of forms, including many types of mental illness. Note that the accounting equation https://www.bookstime.com/articles/virtual-bookkeeping-assistant-for-your-business described in the previous chapter remains in balance. Assets have gone up by $2,000 while the liability side of the equation has also increased by the same amount to reflect the source of this increase in the company’s assets. It’s crucial to review each transaction during an accounting period to ensure accurate recording of financial records. The initial phase of the accounting cycle consists of recording transactions, balancing the books, and reporting financial results to stakeholders.

    ( . Identifying the accounts involved:

    Transaction Analysis: Flyers Trade Walker, Extend Seeler Philadelphia Flyers – NHL.com

    Transaction Analysis: Flyers Trade Walker, Extend Seeler Philadelphia Flyers.

    Posted: Thu, 07 Mar 2024 08:00:00 GMT [source]

    Typically, the individual and the therapist will establish a contract that outlines the desired outcome they wish to achieve in therapy. This may contribute to the person in therapy taking personal responsibility for events that take place during treatment. The individual will generally then become more able to rely on their Adult ego states to identify and examine various thoughts, behaviors, and emotions which might hinder the ability to thrive. An incorrect analysis of business transaction leads to an incorrect journal entry and therefore errors in accounting records.

    Ulterior Transactions
    transaction analysis

    For accrued expenses, such as salary or rent that grow over time, the accounting system can record the amounts gradually as incurred or only at the point of payment. However, the figures to be reported are not transaction analysis impacted by the specific mechanical steps that are taken. The transactional analysis model was not only used for the theoretical approach but also used in practice such as in counselling and therapy purposes.

    • Assets and equity are just two of the six classifications of accounts, the other four being liability, withdrawal, revenue, and expense.
    • TA can be used in short-term therapy, in a brief solution-focused way, or in a more in-depth long-term way to gain more insight into our unconscious world, and improving our relationships with others, and reduce conflict.
    • This is because, under double-entry accounting, each transaction analysis impacts two accounts.
    • Every valid business transaction financially impacts the entity’s financial position.

    Get Your Questions Answered and Book a Free Call if Necessary

    • TA believes that we have three different states or ways of being during interactions, which are; the child ego state, the parent ego state, and the state of adult (Berne, 1957).
    • This is necessary for the proper application of rules of debit and credit on each account.
    • The protagonists in the novel survive by striving (and succeeding) in escaping from “control dramas” that resemble the games of TA.
    • Berne goes on to devote nearly ten more pages to IWFY in Games People Play.
    • Berne went on to discuss other types of transactions, but those will not be discussed here.

    So while an infant needs cuddling, an adult craves a smile, a wink, a hand gesture, or other form of recognition. Berne defined the term recognition-hunger as this requirement of adults to receive strokes. Berne went on to discuss other types of transactions, but those will not be discussed here. Once a reasonable understanding of ego states and Transactional Analysis has been achieved, the games as described in Games People Play can be understood at a whole new level. The other account involved is John’s capital account, which would be credited.
  • Assumptions and principles used in accounting Accounting and Accountability

    Since liabilities, equity (such as common
    stock), and revenues increase with a credit, their “normal” balance
    is a credit. The basic components of even the simplest accounting system are
    accounts and a general ledger. An account is a
    record showing increases and decreases to assets, liabilities, and
    equity—the basic components found in the accounting equation.

    • It would be impossible to prepare statements that could be compared and thus creating chaos in the business and financial world.
    • The accountant should be objective, but when doubt exists, conservatism should be used to break the tie.
    • Business Entity Concept – is the idea that the business and the owner of the business are separate entities and should be accounted for separately.
    • The customer did not pay cash for the service at that time and
      was billed for the service, paying at a later date.
    • So, if management concludes that they won’t be able to remain in the business, the accounting standards do not allow going concern assumptions.

    Accounting assumptions are the three very basic accounting concepts or principles that are assumed to have been followed in the accounting transactions of an entity. So there is a need for a specific notation saying such concepts have been adhered to, it is understood. In simple words, the business only needs to record transactions that are related to it. For instance, if a personal house of the owner is recorded in the financial statements, it will violate an economic entity concept because the personal house of the owner has nothing to do with the business.

    Since the company has provided the service, it would recognise the revenue as earned, even though cash has yet to be collected. It also means that financial statements can be prepared for a group of separate legal corporations that are controlled by one corporation. This group of commonly owned corporations is referred to as the economic entity. The set of financial statements that reports the combined activity of the group is referred to as consolidated financial statements.

    Standardized accounting principles date all the way back to the advent of double-entry bookkeeping in the 15th and 16th centuries, which introduced a T-ledger with matched entries for assets and liabilities. Some scholars have argued that the advent of double-entry accounting practices during that time provided a springboard for the rise of commerce and capitalism. Since accounting principles differ around the world, investors should take caution when comparing the financial statements of companies from different countries. The issue of differing accounting principles is less of a concern in more mature markets. Still, caution should be used, as there is still leeway for number distortion under many sets of accounting principles.

    This concept is important when valuing a transaction for which the dollar value cannot be as clearly determined, as when using the cost principle. Conservatism states that if there is uncertainty in a potential financial estimate, a company should err on the side of caution and report the most conservative amount. This would mean that any uncertain or estimated expenses/losses should be recorded, but uncertain or estimated revenues/gains should not. This gives stakeholders a more reliable view of the company’s financial position and does not overstate income.

    Companies can still suffer from issues beyond the scope of GAAP depending on their size, business categorization, location, and global presence. These figures provide an excellent example of how the inclusion of non-GAAP earnings can affect the overall representation of a company’s success. The first column indicates GAAP earnings, the middle two note non-GAAP adjustments, and the final column shows the non-GAAP totals. With non-GAAP metrics applied, the gross profit, income, and income margin increase, while the expenses decrease.

    How does IFRS differ from GAAP?

    Since the company has
    provided the service, it would recognize the revenue as earned,
    even though cash has yet to be collected. The Financial Accounting Standards Board (FASB), an independent nonprofit organization, is responsible for establishing these accounting and financial reporting standards. The international alternative to GAAP is the International Financial Reporting Standards (IFRS), set by the International Accounting Standards Board (IASB). Although privately held companies are not required to abide by GAAP, publicly traded companies must file GAAP-compliant financial statements to be listed on a stock exchange.

    Constraints are the limitations or boundaries that are necessary for providing information with qualitative characteristics. The basic assumptions and principles discussed earlier have to be modified to make the information useful. Basic principles of Accounting are essential, and these are the general decision-making rules which govern the development of accounting techniques. Rather than mandating accounting rules, each company could voluntarily disclose the type of information that is considered important. When the accounting treatments and methodologies remain the same over a period of several years the management can properly draw conclusions about the performance of a company. It is an important aspect of planning and decision-making functions of management.

    Consistency Principle

    For instance, reserves for the sales return, inventory obsolesce, allowance for doubtful receivables, and amount of depreciation, etc. The company’s management is expected to have reliable regulatory measures to calculate these balances. The going concept has great significance for the stakeholders like shareholders, suppliers, customers, employees, and others as their return depends on its financial stability. Still, the following are some warnings/signs that help to assessability of the business to remain a going concern. As the formula indicates, assets go on the left side of the equation and are debited.

    In Australia, readers of the annual financial statements for publicly listed companies can assume that the information contained within that statement pertain just to that specific financial year, and no other. In the USA, publicly listed firms are required to produce quarterly and annual financial statements. A potential or existing investor wants timely
    information by which to measure the performance of
    the company, and to help decide whether to invest.

    What are the 10 generally accepted accounting principles?

    Recording business transactions when only cash enters or leaves the business is called the ‘cash basis’. The majority of businesses are required to use the accrual basis of accounting. In this what is the difference between a deferral and an accrual explanation we begin with brief descriptions of many of the underlying principles, assumptions, concepts, and qualities upon which the complex and detailed accounting standards are based.

    For reporting purposes, however, the corporations may be considered as one
    business entity because they have a common ownership. In 2006, the FASB began working with the International Accounting Standards Board (IASB) to reduce or eliminate the differences between U.S. GAAP and the International Financial Reporting Standards (IFRS), known as the IASB-FASB convergence project.[15] The scope of the overall IASB-FASB convergence project has evolved over time. The IASB and FASB issued converged standards for accounting topics including Business combinations (2008), Consolidation (2011), Fair value measurement (2011), and Revenue recognition (2014). As of 2022, the convergence project is coming to an end and no new projects will be added to the agenda. While the Codification does not change GAAP, it introduces a new structure—one that is organized in an easily accessible, user-friendly online research system.

    What Are the Generally Accepted Accounting Principles (GAAP)?

    Using the stable dollar assumption creates a difficulty in depreciation accounting. Assume, for
    example, that a company acquired a building in 1975 and computed the 30-year straight-line
    depreciation on the building without adjusting for any changes in the value of the dollar. Thus, the
    depreciation deducted in 2008 is the same as the depreciation deducted in 1975. The company makes
    no adjustments for the difference between the values of the 1975 dollar and the 2008 dollar. Both
    dollars are treated as equal monetary units of measurement despite substantial price inflation over the
    30-year period.

    Understanding GAAP

    Users expect these statements to present the company’s financial operations fairly, completely, and clearly. The accounting profession has attempted to develop a set of generally accepted and universally practiced standards. Under this assumption, accounting transactions are recorded in the books of accounts when they occur. So as opposed to the cash system, in accrual concept, the revenue or expenditure is recognized in the year they are realized. Let’s discuss five basic accounting assumptions to be considered while preparing a financial statement. The Great Depression in 1929, a financial catastrophe that caused years of hardship for millions of Americans, was primarily attributed to faulty and manipulative reporting practices among businesses.

    In the United States, accountants make another assumption regarding money measurement – the
    stable dollar assumption. Under the stable dollar assumption, the dollar is accepted as a
    reasonably stable unit of measurement. Thus, accountants make no adjustments for the changing value
    of the dollar in the primary financial statements. In 1939, urged by the SEC, the American Institute of Certified Public Accountants (AICPA) appointed the Committee on Accounting Procedure (CAP). During 1939 to 1959 CAP issued 51 Accounting Research Bulletins that dealt with a variety of timely accounting problems.

    The SEC not only enforces the
    accounting rules but also delegates the process of setting
    standards for US GAAP to the FASB. The SEC is an independent federal agency that is charged with protecting the interests of investors, regulating stock markets, and ensuring companies adhere to GAAP requirements. The conceptual framework sets the basis for accounting standards set by rule-making bodies that govern how the financial statements are prepared. Here are a few of the principles, assumptions, and concepts that provide guidance in developing GAAP.

  • What Are Accruals? How Accrual Accounting Works, With Examples

    payroll accrual

    For example, you’d use a manual entry if you recently promoted an employee or let someone go. Payroll accounting keeps track of five essential payroll-related costs and obligations. Some senior staffers at the Post — while they may not have to worry about that penalty — have their own fraught history with the pension plan. Starting in 2014, the Bezos-run Post halted accrual of pension benefits for employees who had started at the paper before the 2009 cutoff. “Literally, some people were going to lose hundreds of thousands of dollars,” recalls Fredrick Kunkle, a Metro reporter and former guild co-chair.

    payroll accrual

    Calculating https://www.bookstime.com/s basically means adding up all outstanding payroll liabilities for each employee—and then, of course, adding up those sums to determine the total for the whole of your staff. For accrued revenues, the journal entry would involve a credit to the revenue account and a debit to the accounts receivable account. This has the effect of increasing the company’s revenue and accounts receivable on its financial statements. To calculate accrued payroll, count the amount of hours your employees worked since the last day they were paid. If they are salaried employees, count the number of days they performed salaried work for which they have not yet been compensated. Since businesses don’t normally pay employees immediately, there ends up being a lag time between the end of a pay period and the date the employee is compensated.

    Small Business Owners Guide to Accrued Payroll

    The platform’s ability to manage payments in multiple currencies adds another convenience layer. More importantly, Skuad ensures your organization’s full compliance with different countries’ payroll and employment laws. So, you can focus on your core business operations while Skuad takes care of the intricate aspects of payroll management. This process becomes even more critical when dealing with independent contractors and international employees. Companies must understand the laws of their countries to comply with additional regulations regarding accrued payroll.

    • Just like with commissions and overtime, it’s important to record and monitor all bonuses and incentives that employees earn.
    • Eddy is the all-in-one HR Suite built to help local businesses easily manage their people, payroll, and hiring processes.
    • The remaining 16 hours are still owed to the employee and are, therefore, a liability to the company.
    • As the employer, payroll tax expenses and the withholding amounts are your responsibility.
    • You can quickly subtract advanced payments from the total reimbursement amount.
    • Recording a payroll journal entry can either be done manually or through the use of accounting software.
    • These financial entries are included in the organization’s financial statements through the general ledger, helping to streamline the storing of everything to do with employee wages and more.

    As well as prevent accounting errors such as underpayments, overpayments and also ensures your payroll team stays compliant with regulations. Keeping track of your organization’s spending is fundamental to managing resources successfully. Certain employee benefits, payroll accrual like health and life insurance premiums, retirement contributions, and more, also form part of the accrued payroll. As an employer, if these benefits are to be paid in the next period, they should be included in the current period’s accrued payroll.

    Competitive Pay

    This would be any form of compensation that an employee might receive in return for their work. Most often, that’s monetary with a bi-weekly salary, but it could also look like extra time off, paid time off (PTO), or a bonus. A company may occasionally print manual paychecks to employees, either because of pay adjustments or employment terminations. In other words, you take the expense off the books until you pay for it later in the month.

    • An expense report is similar to a timesheet in that it documents work hours and costs on a daily basis.
    • Instead, the clerk can estimate hours worked based on historical records of hours worked per day, or the standard number of working hours per day.
    • Deposit all withheld payroll taxes and employer-matched taxes at a bank that is authorized to handle these transactions.
    • The IRS allows most businesses that are not corporations to select their payroll accounting method.
    • For example, if a company has a savings account that earns interest, the interest that has been earned but not yet paid would be recorded as an accrual on the company’s financial statements.
    • We’ve already talked about the difference between accrual accounting and cash accounting.

    This proactive approach can prevent substantial financial losses and protect the organization’s reputation. Vacation pay accrual is setting aside money to pay employees for the vacation time they’ve earned but have not taken. Regulations regarding vacation pay accrual vary from country to country, making it a significant factor for organizations operating globally. Bonuses should be included in payroll accruals whenever possible to ensure that the most accurate data is being reported. This means that the hourly-paid employees were last paid on Friday, June 27 for the hours they worked through Saturday, June 21.

    Employee Time Clock

    Accrued payroll is reported as an operating expense in the income statement in the period in which it is incurred, regardless of whether companies have made any cash payments on any owed wages and salaries. When employees work more than their standard working hours, they earn overtime. Since this often isn’t calculated until the end of the pay period, it frequently forms part of the payroll accrual.

  • File and Retain Donation Documents

    how to keep church financial records

    Despite this, most churches turn  profits every year from donations. Keep in mind that every state has different record retention laws. This is something you should confirm for your state so you understand what you need to keep. These records also come in handy when the church needs financial assistance. For instance, if you want to get a loan, you may need certain documentation. Financial record organization is very important when you are running a church.

    how to keep church financial records

    When possible, these reports should be reviewed electronically rather than printed. When printed reports are necessary, they should be carefully managed to respect members’ privacy and to comply with local data protection laws. If you run a nonprofit local church, you might not have a large budget for church management software. Fortunately, some companies like TouchPoint and QuickBooks offer free or discounted software for churches.

    How to Keep Church Financial Records: A Comprehensive Guide

    There are many instances where you may need to prove your church finances and where the money is going. If you have any time cards or timesheets, you need to retain them for two years. Some churches may receive income from church businesses or companies. This money ends up becoming actual income, not a type of donation. The Aplos Team is here to help you accomplish your goals with educational materials that can provide best practices, tips on how to use the software, and examples to inspire you. Records of adopted children may be created or updated only after an adoption is final.

    • Those who prefer to keep things old school or are not very tech-savvy may choose to keep a hard copy of tax records and other documents of importance in a trusty filing cabinet or two.
    • By following these guidelines, churches can ensure that their financial activities are reported accurately and managed responsibly.
    • The basic timelines to follow usually include keeping records permanently or for 10 years.
    • The ward clerk or an assistant ward clerk shows members how to view their membership information in the Member Tools app.
    • The records of members who live in hospitals or care facilities should be in the ward that can best serve them.
    • Choosing the storage option that makes the most sense to your organization will depend on your ministry’s needs.

    Attendance is recorded each week by quorum and organization secretaries and advisers. Members who are serving in the Primary or as youth leaders within the ward are also included as attending. Members who are attending another ward are counted in the ward they https://www.bookstime.com/ attend. And church records management plays an important role in your church’s overall health. This might include filling in the gaps if there’s any missing information, such as missing meeting minutes or official bylaws that haven’t yet been documented.

    Stake Presidency

    In addition, you will generally take less time to search electronic records than paper files, and sending digital records is quicker and less expensive than copying and mailing hard copy records. Typically, courts also now allow digital images to be submitted as evidence in legal proceedings, thus eliminating the need for hard copy documents in court. Organizing and maintaining financial records is essential for churches. To do this, churches should develop an accounting system that works for their specific needs. This system should include procedures for processing payments, managing accounts receivable and payable, and recording transactions. Additionally, churches should establish record-keeping policies to ensure that all financial documents are stored securely.

    how to keep church financial records

    In most cases, that is the ward where the hospital or facility is located. If the member’s location is found, the clerk moves the record accordingly. If the member’s location is not found after using all finding resources, the clerk receives the bishop’s approval to return the record to Church headquarters. Records are not canceled for those who have not been baptized because of an intellectual disability unless requested by the person or a legal guardian, including a parent.

    Avoiding Division: Fostering Unity in Churches

    St. John was successful in soliciting funds to build a new church on the corner of Craig Street and Fifth Avenue, in the heart of the fast developing section of Oakland. His Social Gospel sense of mission however, did not extend as freely to the steel workers in the Homestead Strike of 1892. Prominent members at this time included Mary Semple, Maria and Alice Holdship, George Morgan, James Handy, Robert & Sophia McCargo. De Lange returned for a few years after that, before moving to Meadville, PA. The society went into another remission from that point until the arrival of Rev. James Graham Townsend in 1889.

    This should include what documentation to keep and how long to keep it, as well as where these documents will be stored and how they will later be disposed of. These records also include employee expense reports and personal records after employment separation. The rules for how long you need to keep these records vary according to where your church is located.

    Stake and Ward Technology Specialists

    Her mother saved these letters, which covered a span of nearly ten years, and luckily, they were found by chance among her papers after she died. They are a case in point as to why the archiving of church records is so important. Quorum and organization leaders oversee record keeping in their organizations. They work with secretaries to ensure that records and reports are accurate and timely. Electronic backup in PDF format is the best way to retain this information. Be sure the information is protected in the event of a fire, flood, or computer virus.

    Moreover, the collection and the finding aid have made it possible to know what records are there and how to locate them. “You haven’t an idea of the dirt here,” wrote Martha Elizabeth Everett St. John to her mother in 1891. She was describing life in Pittsburgh after moving to that city with her husband, Charles Elliott St. John, the new minister of the First Unitarian Church.

    Ward members who are not present because they have another assignment or are attending another ward are counted in the ward they attend. He is recommended by the bishopric and called and set apart by a member of the stake presidency or an assigned high councilor. He should hold the Melchizedek Priesthood and have a current temple recommend. A records retention policy sets out how long records must be kept and includes guidelines and processes for how and when to dispose of records. This ensures that everyone involved in managing your church’s records is clear on the procedures and what needs to be kept.

    County Candidates: Responses to Public Questions News … – Chatham Star-Tribune

    County Candidates: Responses to Public Questions News ….

    Posted: Sun, 05 Nov 2023 00:28:00 GMT [source]

    In sexual misconduct cases, some state legislatures have passed special laws allowing allegations dating back 30 years or more regardless of the statute of limitations. For this reason, it’s important to involve an attorney in setting record retention periods for operational records. Like any organization, churches must manage important administrative and record keeping processes, including accounting for churches and how long to keep church financial records. If you run a church, this is an important part of ensuring the church meets state and federal legal requirements.

  • Chelsea 0-2 Brentford, Premier League: Tactical Analysis

    horizontal analysis

    The priority here should be to identify the company’s areas of strengths and weaknesses to create an actionable plan to drive value creation and implement operating improvements. The findings of common size analysis as compiled in the preliminary stages of due diligence are critical. With the financial information in hand, it’s time to decide how to analyze the information. “Mindful of the fact that many Arab governments are worried about legitimacy crises, they can’t be expected to enter the Abraham Accords—at least not any time in the foreseeable future.” There will also be previews of all the matches on the card, analysis, breaking news, and more.

    This type of analysis reveals trends in line items such as cost of goods sold. Whether you do a horizontal analysis quarterly or yearly, it’s worth the time and effort to perform this calculation regularly. You can do horizontal analysis using only two periods for the comparison, but it’s highly recommended you use more to avoid drawing and acting on less accurate conclusions. Financial statements are critical when seeking company partners and securing investment capital.

    Step 3: Identify Trends and Patterns

    External stakeholders use it to understand the overall performance and business value of an organisation, while internal constituents use it as a monitoring tool for managing finances. With , we look at the year-over-year (YoY) change in each line item. For example, in the income statement shown below, we have the total dollar amounts and the percentages, which make up the vertical analysis. Depending on their expectations, Mistborn Trading could make decisions to alter operations to produce expected outcomes. For example, MT saw a 50% accounts receivable increase from the prior year to the current year. If they were only expecting a 20% increase, they may need to explore this line item further to determine what caused this difference and how to correct it going forward.

    A horizontal analysis is most useful when the underlying financial information is consistently reported, based on the applicable financial reporting framework. Examples of these frameworks are generally accepted accounting principles and international financial reporting standards. Ideally, every business within an industry should apply an accounting framework in the same way, so that their reported financial information can be compared.

    AccountingTools

    https://simple-accounting.org/how-to-start-your-own-bookkeeping-business-for/ also makes it easier to compare growth rates and profitability among multiple companies in the same industry. For example, if you run a comparative income statement for 2018 and 2019, horizontal analysis allows you to compare revenue totals for both years to see if it increased, decreased, or remained relatively stagnant. As such, a financial statement analysis provides a comprehensive and unbiased overview of a company’s profitability, value, creditworthiness and financial security.

    Regardless, accounting changes and one-off events can be used to correct such an anomaly and enhance horizontal analysis accuracy. Although a change in accounting policy or the occurrence of a one-time event can impact horizontal analysis, these situations should also be disclosed in the footnotes to the financial statements, in keeping with the principle of consistency. Depending on which accounting period an analyst starts from and how many accounting periods are chosen, the current period can be made to appear unusually good or bad. For example, the current period’s profits may appear excellent when only compared with those of the previous quarter but are actually quite poor if compared to the results for the same quarter in the preceding year. Coverage ratios, like the cash flow-to-debt ratio and the interest coverage ratio, can reveal how well a company can service its debt through sufficient liquidity and whether that ability is increasing or decreasing.

    Horizontals analysis advantages and disadvantages

    Get instant access to lessons taught by experienced private equity pros and bulge bracket investment bankers including financial statement modeling, DCF, M&A, LBO, Comps and Excel Modeling. Crucial Accounting Tips For Small Start-up Business Analyze the information to determine if there are any difficulties or opportunities for the company. This might aid the company in generating effective projects and planning for the future.

    horizontal analysis

  • How to Calculate Retained Earnings + Examples

    how to calculate retained earnings

    This key financial metric provides essential insights into a company’s operational efficiency and profitability. While increasing retained earnings may signal financial stability and growth potential, it doesn’t guarantee future success. Economic, industry, and market conditions can change, impacting a company’s performance. Consider other factors, such as market trends and competitive positioning, when making investment decisions.

    • You need to supplement your main income this month, so you decide to pay yourself $1,500 in cash dividends out of your profits.
    • Depending on the company’s management, they will either create a separate retained earnings statement or sometimes prepare a combined statement of income and earnings.
    • As mentioned earlier, retained earnings appear under the shareholder’s equity section on the liability side of the balance sheet.
    • A company with consistently high net income figures can expect a boost in their retained earnings.
    • It’s essential to distinguish retained earnings from these components for a clearer financial picture.

    Another factor influencing retained earnings is the distribution of dividends to shareholders. When a company pays dividends, its retained earnings are reduced by the dividend payout amount. So, if a company pays out $1,000 in dividends, its retained earnings will decrease by that amount. Retained earnings represent a critical component of a company’s overall financial health, as they indicate the profits and losses the company has retained. By subtracting dividends from net income, you can see how much of the company’s profit gets reinvested into the business. Retained earnings are the portion of a company’s net income that is not paid out as dividends.

    Employer’s (secondary) Class 1 contribution rates for employees under 21

    Retained earnings represent the portion of the net income of your company that remains after dividends have been paid to your shareholders. That is the amount of residual net income that is not distributed as dividends but is reinvested or ‘ploughed back’ into the company. It can also provide insights into whether a company is growing or shrinking.

    • If your business is small or young, it might seem that using retained earnings in this way makes complete sense – and you’d be right.
    • In this article, we’ll delve into the fundamentals of Retained Earnings, explaining what it is, how to calculate it, and why it matters.
    • When in doubt, please consult your lawyer tax, or compliance professional for counsel.
    • Doing so will ensure that your company uses its earnings efficiently and maintains the right balance between growth and profitability.

    Cost of sales includes the cost of the goods sold and the cost of production like direct labour. It is important to note that this does not include marketing or administrative expenses. Sales revenue is the amount of money that a company earns from the sale of its products or services. Get instant access to video lessons taught by experienced investment bankers.

    Find your beginning retained earnings balance

    Learn financial statement modeling, DCF, M&A, LBO, Comps and Excel shortcuts. Upon combining the three line items, we arrive at the end-of-period balance – for instance, Year 0’s ending balance is $240m. For our retained earnings modeling exercise, the following assumptions will be used for https://intuit-payroll.org/the-accounting-equation-a-beginners-guide/ our hypothetical company as of the last twelve months (LTM), or Year 0. Without it, many companies would have to borrow extensively from banks, or flounder in the market. Retained earnings is one of those financial matters that might not seem important for smaller or newer businesses.

    No matter how they’re used, any profits kept by the business are considered retained earnings. While paying dividends can be beneficial for shareholders, it can be harmful to the company’s long-term prospects. Best personal finance software of 2023 It may be difficult for a company to expand and grow if it is constantly paying out dividends. As a result, it is essential for businesses to carefully consider whether paying dividends is the right decision.

    Retained Earnings and Stock Dividends

    Companies will also usually issue a percentage of all their stock as a dividend (i.e. a 5% stock dividend means you’re giving away 5% of the company’s equity). Stock dividends require us to do a bit more work and adjust our formula a bit. We have to figure out how much those shares are worth in terms of fair market value (FMV) to make our retained earnings formula work.

    Retained earnings could be used for funding an expansion or paying dividends to shareholders at a later date. Retained earnings are related to net (as opposed to gross) income because it’s the net income amount saved by a company over time. Profits give a lot of room to the business owner(s) or the company management to use the surplus money earned. This profit is often paid out to shareholders, but it can also be reinvested back into the company for growth purposes. Let’s look at this in more detail to see what affects the retained earnings account, assuming you’re creating a balance sheet for the current accounting period.

    Dividend Allowance

    While the term may conjure up images of a bunch of suits gathering around a big table to talk about stock prices, it actually does apply to small business owners. Over 1.8 million professionals use CFI to learn accounting, financial analysis, modeling and more. Start with a free account to explore 20+ always-free courses and hundreds of finance templates and cheat sheets. This represents an increase of over £1,800 to the annual earnings of a full-time worker on the NLW and is expected to affect more than 2.7 million low-paid workers, many of whom work in the care sector. Mr Hunt made reference to protecting the long-term sustainability of the health service, including the publication of the first NHS Long Term Workforce Plan, in his statement on Wednesday. Following the end of the Heavy Goods Vehicle levy suspension period, the new reformed Heavy Goods Vehicle levy comes into effect from 1 August 2023.

  • 12 3 Define and Apply Accounting Treatment for Contingent Liabilities Principles of Accounting, Volume 1: Financial Accounting

    It all depends on the type of liability and the event that ends up occurring. The basic nature of contingent liability is important to know, recognize, and understand. There are three primary conditions that need to be met for a contingent liability to exist. The outcome of the pending obligation is known and the value can be reasonably estimated.

    • Get instant access to lessons taught by experienced private equity pros and bulge bracket investment bankers including financial statement modeling, DCF, M&A, LBO, Comps and Excel Modeling.
    • A contingency occurs when a current situation has an outcome that is unknown or uncertain and will not be resolved until a future point in time.
    • Remote (not likely) contingent liabilities are not to be included in any financial statement.
    • Here, it becomes necessary to notify it to shareholders and other users of financial statements because the outcome will have an impact on investment related decisions.
    • First, it must be possible to estimate the value of the contingent liability.

    A contingent liability is a potential loss that may occur at some point in the future, once various uncertainties have been resolved. The exact status of a contingent liability is important when determining which liabilities to present in the balance sheet or in the attached disclosures. It is of interest to a financial analyst, who wants to understand the probability of such an issue becoming a full liability of a business, which could impact its status as a going concern. As well, pending lawsuits are also considered contingent liabilities because the outcome of the lawsuit is entirely unknown.

    For example, investors might determine that a company is financially stable enough to absorb potential losses from a contingent liability and still decide to invest in it. But a contingent liability needs to be large enough to be able to truly affect a company’s share price. Although it is not realized in the books of accounts, a contingent liability is credited to the accrued liabilities account in the journal. Even if the outcome is based on the probability of occurrence of the event, it is considered an actual liability.

    How Do Liabilities Become Contingent Liabilities?

    Contingent liabilities adversely impact a company’s assets and net profitability. The company sets an accounting entry to debit (increase) legal expenses for $5 million and credit (raise) accrued expenses for $5 million on the balance sheet because the liability is probable and simple to estimate. Let’s expand our discussion and add a brief example of the calculation and application of warranty expenses. The analysis of contingent liabilities, especially when it comes to calculating the estimated amount, is sophisticated and detailed. To make sure a business’s financial reports comply with regulations, a public accounting firm must assess these reports.

    • Therefore, it is also important to describe the liability in the footnotes that accompany the financial statements.
    • In this situation, no journal entry or note disclosure in financial statements is necessary.
    • Others interested in their work can take a license to produce or publish their work.
    • A great example of the application of prudence would be recognizing anticipated bad debts.
    • A subjective assessment of the probability of an unfavorable outcome is required to properly account for most contingences.
    • When no amount within the range is a better estimate than any other amount, however, the minimum amount in the range should be accrued.

    Any use, duplication, or publication of the copyrighted material without the permission of the owner can lead to serious legal charges. The damages that need to be compensated by the party if and when there is a breach in the contract. The breach is usually a failure in the contract or not up to the mark performance by the party.

    AccountingTools

    If the contingency is reasonably possible, it could occur but is not probable. Since this condition does not meet the requirement of likelihood, it should not be journalized or financially represented within the financial statements. Rather, it is disclosed in the notes only with any available details, financial or otherwise. A contingent liability is not recognised in the statement of financial position.

    IAS 37 Provisions, Contingent Liabilities and Contingent Assets

    In this case, a note disclosure is required in financial statements, but a journal entry and financial recognition should not occur until a reasonable estimate is possible. GAAP accounting rules require probable contingent liabilities—ones that can be estimated and are likely to occur—to be recorded in financial statements. Contingent liabilities that are likely to occur but cannot be estimated should be included in a financial statement’s footnotes. Remote (not likely) contingent liabilities are not to be included in any financial statement. Contingent liabilities must pass two thresholds before they can be reported in financial statements.

    Reporting Requirements of Contingent Liabilities and GAAP Compliance

    Contingent liabilities also can negatively affect share price, depending on the probability of the event and other factors. If the company has a strong cash flow and its earnings are high, the liability may not be as important. That said, there can be a variety of techniques to use to help evaluate contingent liabilities and weigh their risk. These can include expected loss estimation, risk simulations of impacts, and pricing methodology. One major difference between the two is that the latter is an amount you already owe someone, whereas the former is contingent upon the event occurring.

    Finally, how a loss contingency is measured varies between the two options as well. Under US GAAP, the low end of the range would be accrued, and the range disclosed. An example of determining a warranty liability based on a percentage of sales follows. The sales price per soccer goal is $1,200, and Sierra Sports believes 10% of sales will result in honored warranties. The company would record this warranty liability of $120 ($1,200 × 10%) to Warranty Liability and Warranty Expense accounts. Contingent liabilities also include obligations that are not recognised because their amount cannot be measured reliably or because settlement is not probable.

    Since this warranty expense allocation will probably be carried on for many years, adjustments in the estimated warranty expenses can be made to reflect actual experiences. Also, sales for 2020, 2021, 2022, and all subsequent years will need to reflect the same types of journal entries for their sales. In essence, as long as Sierra Sports sells the goals or other equipment and provides a warranty, it will need to account for the warranty expenses in a manner similar to the one we demonstrated.

    However, unless the possibility of an outflow of economic resources is remote, a contingent liability is disclosed in the notes. An entity recognises a provision if it is probable the fed monetized more than half the massive federal pandemic debt that an outflow of cash or other economic resources will be required to settle the provision. If an outflow is not probable, the item is treated as a contingent liability.

    Items can be considered to have a monetary value if their inclusion or exclusion has an impact on the business. In our case, we make assumptions about Sierra Sports and build our discussion on the estimated experiences. Warranties arise from products or services sold to customers that cover certain defects (see Figure 12.8). It is unclear if a customer will need to use a warranty, and when, but this is a possibility for each product or service sold that includes a warranty. The same idea applies to insurance claims (car, life, and fire, for example), and bankruptcy.

  • Inventory Records: 4 Ways to Maintain Valid Inventory Books

    Direct-to-consumer organizations can expand their customer base by using marketplaces and social media channels to offer their products directly to consumers. It is why many retailers use a multichannel stock management system, which keeps stock levels across sales channels and provides all data in one place for easy reference. Reducing excess stock and obsolete inventory can help eliminate spoilage and remove added storage costs.

    • Maintaining inventory records independently as your company starts to grow can be a challenge so it is beneficial to partner with a 3PL company like WareIQ.
    • WareIQ has a custom WMS that tracks inventory automatically and can generate reports whenever you need them.
    • While inventory is a crucial aspect of business, it is essential to remember that not all inventory is created equal.
    • Limit access to inventory supply and implement procedures for receiving and shipping.
    • Businesses can gain valuable insights into their purchasing and fulfillment operations by tracking raw materials, finished goods, and packing materials.

    As you know by now, debits and credits impact each type of account differently. Some common inventory management challenges are changing demand, supply chain complexity, and increasing competition. To overcome them and succeed, you’ll need to stay on top of the latest trends in the industry. Raw materials are the parts used to create a product, work-in-progress refers to partially completed items, and finished goods are ready to be sold.

    The concept of the records series is applicable to nontextual as well as textual records. For example, a group of contract files in a procurement office would constitute one series and thus an inventory item. Other series in that office might include general correspondence, procurement reports from regional offices, and a file on individual employees. Of the two systems, the perpetual inventory system is regarded as the costlier one. However, it provides better information in comparison to the periodic inventory system. Before creating an inventory plan it is imperative to know what constitutes a record within the city, county, state, and/or country in which it is located.

    Inventory Accounting- Process, Explanation, Practices

    Inventory management is critical for any business that relies on raw materials or finished goods to produce its products. By tracking the lifecycle of these items, businesses can ensure that they have enough stock on hand to meet customer demand without overproducing and incurring unnecessary costs. Inventory accounting is recording, classifying, and summarizing inventory data for financial reporting purposes. It includes both the physical count of inventory and the valuation of inventory.

    • The duration for retaining inventory records varies depending on the jurisdiction’s laws in each state.
    • Reversals of writedowns are recognized in profit or loss in the period in which the reversal occurs.
    • Reducing excess stock and obsolete inventory can help eliminate spoilage and remove added storage costs.
    • If your inventory management system is too basic or lacking the features you need, your inventory accuracy could be suffering.
    • By performing a physical inventory, units can ensure that the university presents accurate and Consolidated financial information.

    This helps prevent loss or theft, making it easier to track down specific items if needed. By keeping a well-organized warehouse, businesses can ensure their inventory is always controlled. Additionally, businesses can use object codes to efficiently identify inventory purchases and sales. A cost-of-goods-sold transaction can then be used to transfer the cost of goods sold from the inventory account to the operating account. Inventory accounting is the practice of keeping track of the value of inventory items through their respective production stages.

    The GAAP guidelines also prevent a corporation from overstating its worth by overstating the value of its inventory. For brands looking to store inventory and fulfill orders within their own warehouses, ShipBob’s warehouse management system (WMS) can provide better visibility and warehouse organization. That’s why online brands ditch the manual work and implement technology that makes record-keeping a breeze. At the same time, the US has pushed Big Tech to move certain production mechanisms back to American soil.

    Scope of onerous contracts requirements is broader under IFRS Standards than US GAAP

    As a result, it is important to understand how inventory accounting works to ensure that your financial statements are accurate. You may also consult with your accountant about the appropriate inventory valuation technique based on the products you sell and your average sales volume. To run a successful business, you must keep your inventory precise, simplified, and up to date at all times. When you lose grasp of your inventory, you instantly lose control of your company’s profitability. Furthermore, out-of-stock situations usually result in customer displeasure and losses for businesses.

    Why it’s important to keep up-to-date inventory records

    An inventory of an agency’s documents is required as part of a successful records management program, as is the identification of present retention schedules or the design of new retention schedules for those records. Retention schedules identify the records that an agency needs to preserve and specify minimum retention periods based on the records’ legal, fiscal, administrative, and historical significance. Once all retention obligations have been met, the records must then be properly disposed of. Keeping records just “because that is how we have always done it” just is not an acceptable response and retaining records past the required retention period will result in a non-compliant records management program. Although an investment of this kind might incur higher overhead costs, you may end up saving money, in the long run, thanks to greater inventory accuracy.

    Perpetual Inventory System

    To help keep track of inventory, you need to learn how to record inventory journal entries. Inventory management best practices can help businesses of all sizes to streamline their operations, keep track of their assets, and improve their bottom line. From correctly balancing stock in warehouses to ensuring production can continue to flow, inventory management is essential for keeping businesses up and running.

    The record series concept is a convenient way of grouping file units or documents to permit their management as a group. The unit to be inventoried and scheduled is normally the record series, not individual documents or file folders. As a manufacturing entity may consist of inventories raw material, work-in-process and finished goods. On the other hand, the trading entity includes products bought for the purpose of resale in their existing state.

    Under the LIFO cost flow assumption, the inventory will be valued at the older costs, since the more recent costs are assumed to be the first costs to flow out of inventory. Not to mention, purchases and returns are immediately recorded in your inventory accounts. Staff scans the barcode or RFID tag using a mobile scanner when new products arrive. This allows each product type to be stored in its designated area and makes it easier to track stock levels. If you have too much inventory on hand, it can tie up valuable resources and lead to storage issues. On the other hand, if you don’t have enough inventory, you risk running out of products and losing sales.

    The inventory management technology automatically aggregates data, allowing you to generate custom reports on demand. The inventory record is an important document showing the inventory status, data about stock items, how to get a business appraised and the order quantity with regulations. Since the unit cost of items purchased or produced may be increasing with inflation, the costs used for inventory reporting will be based on a cost flow assumption.

    By taking these steps, you can be confident that your inventory records are accurate and up-to-date. Units should take inventory to get an accurate count and consolidate it into one report. By performing a physical inventory, units can ensure that the university presents accurate and Consolidated financial information. You must record the sale on your operating account when selling inventory to a non-dept entity or individual. If you sell inventory and record an accounts receivable, you must use an accounts receivable object code. Inventory is an asset, and as such, it can significantly impact the bottom line.

    However, all transactions must be completed by June 30th to accurately calculate the cost of goods sold. Departments are also responsible for ensuring that all inventory items are adequately safeguarded from loss or damage. After the physical count is complete, the data must be classified and summarized.

    A system of ascertaining the value of inventory in which the inventory balances are entered after every receipt and issue of stock. In addition to this, physical inventory is checked and compared with the balances shown in the books to date, to ensure reliability and accuracy. One of the major limitations of the physical count is that normal business operations are hampered during the process of physical verification of stock. Hence it is not easy to recognize the loss of stock, out of damage, theft or pilferage. The valuation of inventory is based on cost or net realisable value whichever is lower.

  • Understanding Methods and Assumptions of Depreciation

    The balance in the Equipment account will be reported on the company’s balance sheet under the asset heading property, plant and equipment. To illustrate the cost of an asset, assume that a company paid $10,000 to purchase used equipment located 200 miles away. The company then paid $2,000 to transport the equipment to its location. Finally, the company paid $5,000 to get the equipment in working condition. The company will record the equipment in its general ledger account Equipment at the cost of $17,000.

    • The company will continue to record the depreciation expense in the income statement for the next 10 years.
    • An amortization schedule is often used to calculate a series of loan payments consisting of both principal and interest in each payment, as in the case of a mortgage.
    • Thus, companies use different depreciation methods in order to calculate depreciation.
    • $3,200 will be the annual depreciation expense for the life of the asset.
    • On the other hand, a larger company might set a $10,000 threshold, under which all purchases are expensed immediately.

    Even if you defer all things depreciation to your accountant, brush up on the basics and make sure you’re leveraging depreciation to the max. Harold Averkamp (CPA, MBA) has worked as a university accounting instructor, accountant, and consultant for more than 25 years. Upgrading to a paid membership gives you access to our extensive collection of plug-and-play Templates designed to power your performance—as well as CFI’s full course catalog and accredited Certification Programs. Our partners cannot pay us to guarantee favorable reviews of their products or services.

    Use of Contra Account

    The straight-line depreciation method is the most widely used and is also the easiest to calculate. The method takes an equal depreciation expense each year over the useful life of the asset. Using this new, longer time frame, depreciation will now be $5,250 per year, instead of the original $9,000. That boosts the income statement by $3,750 per year, all else being the same.

    After three years, the company changes the expected useful life to a total of 15 years but keeps the salvage value the same. With a book value of $73,000 at this point (one does not go back and “correct” the depreciation applied so far when changing assumptions), there is $63,000 left to depreciate. This will be done over the next 12 years (15-year lifetime minus three years already). The second scenario that could occur is that the company really wants the new trailer, and is willing to sell the old one for only $65,000. The first two are the same as above to remove the trailer from the books.

    How Does Depreciation Differ From Amortization?

    There are several methods for calculating depreciation, generally based on either the passage of time or the level of activity (or use) of the asset. The asset’s cost minus its estimated salvage value is known as the activity-based management asset’s depreciable cost. It is the depreciable cost that is systematically allocated to expense during the asset’s useful life. This formula is best for small businesses seeking a simple method of depreciation.

    This method also calculates depreciation expenses using the depreciable base (purchase price minus salvage value). Instead of realizing the entire cost of an asset in year one, companies can use depreciation to spread out the cost and match depreciation expenses to related revenues in the same reporting period. This allows the company to write off an asset’s value over a period of time, notably its useful life. To get around this linkage problem, we assume a steady rate of depreciation over the useful life of each asset, so that we approximate a linkage between the recognition of revenues and expenses over time. Also, the matching principle does not work in those cases where depreciation expense is recognized but there are no sales, as occurs in seasonal sales situations. Another accelerated depreciation method is the Sum of Years’ Digits Method.

    A deduction for the full cost of depreciable tangible personal property is allowed up to $500,000 through 2013. When an asset is sold, debit cash for the amount received and credit the asset account for its original cost. Under the composite method, no gain or loss is recognized on the sale of an asset.

    The units-of-production method depreciates equipment based on its usage versus the equipment’s expected capacity. The more units produced by the equipment, the greater amount the equipment is depreciated, and the lower the depreciated cost is. The depreciated cost can be used as an asset valuation tool to determine the useful value of an asset at a specific point in time.

    Understanding Methods and Assumptions of Depreciation

    GAAP is a set of rules that includes the details, complexities, and legalities of business and corporate accounting. GAAP guidelines highlight several separate, allowable methods of depreciation that accounting professionals may use. This method, which is often used in manufacturing, requires an estimate of the total units an asset will produce over its useful life. Depreciation expense is then calculated per year based on the number of units produced that year.

    The Capitalization Limit

    The depreciated cost can also be calculated by deducting the sum of depreciation expenses from the acquisition cost. In some cases, it makes more sense to calculate depreciation by measuring the work the asset does, rather than the time it serves. So, in this depreciation method, equal expense rates are assigned to each unit of production, meaning that depreciation is based on output capacity rather than number of years. There are two steps you’ll need to go through to calculate units of production depreciation. The four depreciation methods include straight-line, declining balance, sum-of-the-years’ digits, and units of production.

    Recording Accounting Depreciation in Books

    The two main assumptions built into the depreciation amount are the expected useful life and the salvage value. 10 × actual production will give the depreciation cost of the current year. Suppose an asset has original cost $70,000, salvage value $10,000, and is expected to produce 6,000 units. To make the topic of Depreciation even easier to understand, we created a collection of premium materials called AccountingCoach PRO. Our PRO users get lifetime access to our depreciation cheat sheet, flashcards, quick tests, quick test with coaching, business forms, and more. SmartAsset Advisors, LLC (“SmartAsset”), a wholly owned subsidiary of Financial Insight Technology, is registered with the U.S.

    Regardless of the depreciation method used, the total amount of depreciation expense over the useful life of an asset cannot exceed the asset’s depreciable cost (asset’s cost minus its estimated salvage value). Depreciation is necessary for measuring a company’s net income in each accounting period. To demonstrate this, let’s assume that a retailer purchases a $70,000 truck on the first day of the current year, but the truck is expected to be used for seven years. It is not logical for the retailer to report the $70,000 as an expense in the current year and then report $0 expense during the remaining 6 years. However, it is logical to report $10,000 of expense in each of the 7 years that the truck is expected to be used. The depreciated cost of an asset is the value that remained after the asset’s been depreciated over a period of time.

    Here are four common methods of calculating annual depreciation expenses, along with when it’s best to use them. Accumulated depreciation is reported on the balance sheet as a negative number in the asset section, reducing the overall value of the fixed assets owned by the company. The purpose of depreciation is to match the expense recognition for an asset to the revenue generated by that asset. You need to determine a suitable way to allocate cost of the asset over the periods during which the asset is used. Generally, the method of depreciation to be used depends upon the patterns of expected benefits obtainable from a given asset. This means different methods would apply to different types of assets in a company.

  • QuickBooks Online Plans Comparison: 2023 Pricing & Subscription Levels

    This plan adds up to three users to the account so that the right people have access to data at their fingertips. It also gives you bill management and collects employee time for invoices to add them for proper billing. It’s a great fit if you’ll be doing the bookkeeping yourself and don’t need inventory accounting. If you choose to cancel your QuickBooks Online subscription, you will still have access to your QuickBooks Money account and data. Yes, QuickBooks Online offers good value for its price across all plans.

    • This plan is intended for fast-growing service-based businesses.
    • For $1,410 per year, get the Enterprise plan with advanced pricing, reporting and inventory.
    • Customer Support is included and available via live chat and email.
    • QuickBooks Self-Employed is a “lite” version of the Online product that’s ideal for people who earn income from a variety of sources and helps to separate personal and business finances.

    If you deal with inventory or large projects heavily, Plus is the best option. However, self-employed persons should consider Self-Employed—unless they have an employee, which will require an upgrade to Simple Start. If your business is service-based without any inventory, then Essentials should provide everything you need while saving you $30 per month compared to Plus. If you’re scaling from five to 25 users, then go with Advanced. With QuickBooks Essentials, you can track billable time by job and assign it to a specific customer—something you can’t achieve with Simple Start.

    Have QuickBooks Desktop?

    Simple Start runs basic reports, including cash flow statements, profit and loss (P&L) statements, and balance sheets. Some of the other 20-plus built-in standard reports available include P&L by month and customer, quarterly P&L summaries, and general ledger. Read our full QuickBooks Checking review for more information.

    Integrations are third-party add-ons that give you additional features and capabilities. QuickBooks Online has over 750 integrations to choose from, including common software programs, such as Shopify, Gusto, and Mailchimp. I use QuickBooks on a daily basis for invoicing clients, bank reconciliation as well as looking at the various reports. I have customised the reports to show the time period and categories that are useful for our business.

    Additionally, QuickBooks Essentials will send reminders regarding upcoming bills to be paid so that you don’t miss a payment. Rates and fees vary depending on whether you accept payments through QuickBooks Online, QuickBooks Desktop, QuickBooks POS or the GoPayment app. Promotions may be available for businesses that charge more than $7,500 per month, and 30-day free trials are also available. There is a $25 chargeback fee and PCI compliance service costs $9.95 per month. QuickBooks Desktop is more traditional accounting software that you download and install on your computer, while QuickBooks Online is cloud-based accounting software you access through the internet.

    If comparing estimated costs to actual job costs is critical to your business, check out Xero. Plus allows you to assign classes and locations to your transactions, so you can see how your business performs across divisions, locations, rep areas, or any units that are relevant to your business. If you run businesses in multiple locations and you want to see which one is most profitable, an upgrade to Plus from Essentials is worth the price. Intuit typically offers deals where new users can get a discount on QuickBooks Payroll by bundling it with a QuickBooks Online subscription. This service gives you access to a QuickBooks debit card, cash flow forecasting, and QuickBooks Envelopes, which is a place to set aside savings. Here’s a complete breakdown of what’s included with each QuickBooks Online pricing plan.

    How do I get QuickBooks Online for free?

    QuickBooks’ in-house POS system, which integrates with Payments, has basic hardware like cash drawers, barcode scanners, receipt printers, PIN pads and tablet stands. These options are sufficient for some small retail businesses, but not those with more complicated requirements. For example, QuickBooks doesn’t offer an in-house kitchen display system or separate customer-facing display screen, a potential deal-breaker for cafes and restaurants.

    App integration

    Afterward, continue reading our article for a more detailed comparison of the five QuickBooks Online versions. In addition to the monthly subscription price, there are united nations civil society participation a few other QuickBooks Online charges to be aware of. Intuit is not always the most forthcoming about these extra fees, which is why we want to highlight them now.

    Meet your clients’ needs faster, using the tools you know

    QuickBooks offers a free one-on-one meeting with a QuickBooks ProAdvisor for new users. Your ProAdvisor will help you set up your company file, including adding your business information, setting up accounts, and connecting your bank accounts. QuickBooks Online Self-Employed works very well for people who work for themselves in a service industry and report their business income on Schedule C of their personal income tax return. We even consider it the best for tracking freelance income and filing tax returns in our guide to the best accounting software for freelancers.

    QuickBooks Desktop

    This is especially useful if you have many expenses to record, such as business travel expenses, office supplies, and equipment purchases. You can upload expense receipts in bulk, categorize them according to the appropriate expense account, and then submit them for approval. Nonetheless, Plus has an advanced job costing capability, which is helpful for construction and contracting firms.

    A Live Bookkeeper cannot begin cleaning up your past books until they receive the required supporting documentation, which your bookkeeper will request from you after your first meeting. Once your bookkeeper receives all the necessary documentation, they’ll typically complete your cleanup within 30 days. In some cases, your cleanup may take longer depending on timeliness of documentation and the complexity of your books. Learn about the two ways on how to add customers in QuickBooks in order to easily invoice along with autofill information on sales forms. Learn about the different ways you can record your spending, how to record and categorize your spending and the difference between bills, bill payments, expenses, and checks in QuickBooks. Learn how to send reminders to customers when invoices are overdue, and also how to set up batch actions to send multiple invoice reminders in QuickBooks.

    All Online plans include receipt capture, QuickBooks support and more than 650 app integrations with apps such as PayPal, Square and Shopify. For $27.50 per month for the first three months, then $55 per month after that, get up to three users, manage and pay bills and track time with its Essentials plan, which is its most popular plan. QuickBooks also allows you to add a button to accept payments directly from the invoicing tool with credit cards and debit cards or automated clearing house e-checks. Both this feature and the invoice customization tools are now expected of accounting software platforms, but we felt that QuickBooks’ tools were especially strong.

    QuickBooks Video Tutorials

    QuickBooks Online automatically backs up your data, so you never worry about whether your books are safe and up to date. Do you want to get a better understanding of accounting jargon? Check out our glossary for helpful definitions of common accounting terms. Tax deduction tools help ensure you take all available deductions and maximize the allowed amount to reduce your tax liability. Kashoo’s inbox feature is basically a central repository that shows your imported transactions.